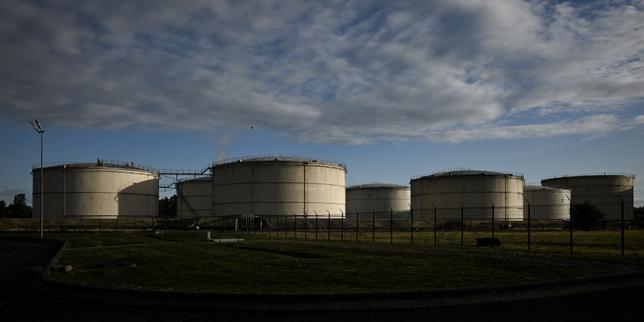
Crude oil exports from the Middle East just hit 12.8 million barrels per day. That marks the highest volume recorded since the US-Israeli war with Iran broke out in February. On paper, it sounds like a massive supply relief for an anxious global market.
Don't let the headline numbers fool you. You might also find this similar story insightful: What Everyone Is Missing About The New Fifteen Billion Dollar Trump Steel Deal.
Analytics firms like Kpler paint a picture of a partial rebound, but the actual plumbing of global energy tells a much more fragile story. Shipments are recovering because producers are frantically rerouting flows, not because the region has returned to normal business. If you look past the immediate surge, you'll see a supply chain operating under severe structural stress.
The Strait of Hormuz and the Great Reroute
Saudi Arabia is driving much of this September volume recovery, but the mechanics behind it reveal deep vulnerability. Following attacks that damaged parts of the critical East-West pipeline, Riyadh had to shift its export loadings away from the Red Sea port of Yanbu. Instead, barrels are pouring back into the Persian Gulf. As highlighted in detailed coverage by Investopedia, the effects are significant.
Shipments from Ras Tanura spiked to roughly 3.6 million barrels per day in September, a massive jump from August's depressed figures of around 929,000 barrels. Total Saudi crude exports surged to 5.4 million barrels per day. Behind that jump lie logistics reports showing nineteen very large crude carriers loaded with two million barrels each pushing out through the Strait of Hormuz in a single week.
That chokepoint handles about 7.4 million barrels per day of the region's current output. When that much crude funnels through such a narrow maritime corridor, any localized disruption turns from a regional headache into a global pricing crisis overnight.
The Six Million Barrel Ghost Gap
A monthly average of 12.8 million barrels per day sounds impressive until you compare it to pre-war reality. Back in February, before the conflict triggered regional disruptions, combined exports from major regional producers sat at roughly 18.8 million barrels per day.
That leaves a persistent deficit of 6 million barrels per day.
This gap explains why physical markets remain tight even as headline output numbers tick upward. Refineries across Asia and Europe aren't swimming in cheap crude. They're scrambling for spot cargoes to cover persistent shortfalls. The recovery is only halfway finished, and the remaining ground to cover requires infrastructure repairs that will take weeks, if not months, to complete.
What Market Participants Keep Missing
Traders often react to headline production data with knee-jerk sell-offs, assuming that rising export volumes mean the crisis is over. That approach ignores the fragile routing keeping those tankers moving. When production relies on temporary workarounds and emergency pipeline fixes, operational risk stays permanently elevated.
If you are tracking energy markets or managing industrial procurement right now, stop treating headline export volumes as a clean bill of health. Monitor regional infrastructure repair timelines and watch tanker tracking data through the Persian Gulf closely. The real story isn't that exports are up. The story is how easily the next bottleneck could wipe out those gains.